
This guide covers condominium insurance in the United States. Master policy structures, coverage splits, and loss assessment limits vary by HOA and by state, so review your specific association’s master policy alongside this general overview.
Owning a condo comes with a common misconception that trips up a lot of first-time buyers: assuming the HOA’s master insurance policy has you fully covered. It doesn’t, and the gap between what that master policy protects and what’s actually your responsibility is exactly what a condo, or HO-6, policy exists to fill.
Two Policies, One Building
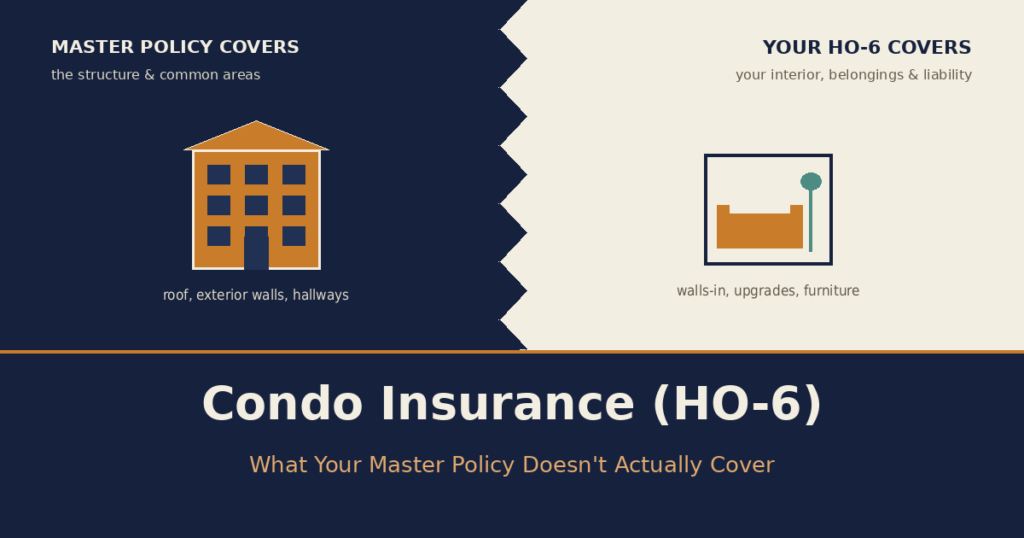
Condo insurance works as a partnership between two separate policies. The homeowners association carries a master policy covering the building’s shared structure and common areas: hallways, the roof, elevators, the lobby, and similar shared spaces. You, as the unit owner, carry your own HO-6 policy covering everything on your side of that boundary: your unit’s interior, your belongings, and your personal liability.
Where exactly that boundary falls depends entirely on how your specific association’s master policy is written. This is the detail that causes the most confusion, and it’s worth understanding before you assume you know what’s covered.
Why “Bare Walls” vs. “All-In” Changes Everything
Master policies generally fall into a few structural types, and the difference matters enormously for how much HO-6 coverage you actually need.
Under a “bare walls-in” master policy, the association’s coverage stops at the unfinished structure, the studs, essentially. You’re responsible for insuring everything from the bare walls inward: drywall, flooring, cabinetry, fixtures, and built-in appliances. Under an “all-in” or “single entity” master policy, the association’s coverage extends further, often including original builder-grade finishes, leaving you responsible mainly for any upgrades or improvements you’ve made beyond that baseline. Many associations fall somewhere between these two structures, split according to their specific bylaws.
If you’ve renovated your unit, upgraded flooring, remodeled a kitchen, added custom built-ins, those improvements typically aren’t covered by an “all-in” master policy beyond its original baseline, and definitely aren’t covered under a “bare walls-in” structure. Your HO-6 dwelling coverage needs to reflect the actual value of what you’d need to rebuild, not just a generic estimate, or you risk being underinsured on your own improvements specifically.
What an HO-6 Policy Actually Covers
A standard condo policy generally includes several core components.
Interior and improvements. This covers your unit’s interior, and depending on your master policy’s structure, potentially your improvements beyond the association’s baseline coverage.
Personal property. Your belongings, furniture, electronics, clothing, are never covered by the master policy. This is entirely your responsibility under your own HO-6 policy.
Liability. If someone is injured inside your unit, or you’re otherwise personally liable for an incident, this coverage responds, similar to how liability works in a standard homeowners policy.
Loss of use. If your unit becomes temporarily uninhabitable due to a covered loss, this helps cover additional living expenses while repairs are underway.
Loss assessment. This is the piece condo owners most commonly overlook, and it’s often described as the most important part of an HO-6 policy.
Why Loss Assessment Coverage Deserves Special Attention
If a covered loss affects a shared area, and the damage exceeds the master policy’s coverage limit or falls within a deductible the association can’t fully absorb, the HOA may pass the remaining cost on to unit owners through a special assessment. Loss assessment coverage on your HO-6 policy can reimburse you for your share of that charge.
Here’s the detail that catches people off guard: many standard HO-6 policies include only a modest amount of loss assessment coverage by default, sometimes as little as $1,000. Several insurance professionals recommend raising this limit considerably, into a range of $25,000 to $50,000 or more, particularly in areas where master policy deductibles have been rising due to increased claims costs from severe weather or water damage. A relatively small default limit can leave a real gap if your association ever faces a significant shared-area loss.
What Standard Condo Insurance Doesn’t Cover
Like a standard homeowners policy, HO-6 coverage carries its own exclusions. Common ones include earthquake damage, flood damage, and damage from pests or general wear and tear, none of which are covered by a standard policy and generally require separate coverage or an endorsement if you want protection against them.
It’s also worth remembering that condo insurance never covers damage to the building’s actual shared spaces or anything the association itself owns. That responsibility sits entirely with the master policy, regardless of how comprehensive your own HO-6 coverage is.
Is It Actually Required?
Condo insurance isn’t required by law in the way liability auto insurance is. In practice, though, it’s close to mandatory for most owners. Most mortgage lenders require an HO-6 policy sufficient to repair your unit to its pre-loss condition as a condition of the loan, reflecting broader industry servicing standards for condo financing. Many condo associations also require unit owners to carry it directly, independent of any lender requirement, specifically because of the loss assessment exposure a single uninsured owner can create for the wider building.
A Practical Example
Imagine a fire in a shared hallway causes $100,000 in damage, and the HOA’s master policy carries a $50,000 deductible. To cover that gap, the association issues a special assessment, charging each unit owner a share of the shortfall.
An owner with adequate loss assessment coverage on their HO-6 policy gets that charge reimbursed, up to their policy’s limit. An owner without that coverage, or with only the low default limit many policies start with, pays the assessment entirely out of pocket.
Now imagine a separate scenario: a burst pipe damages one owner’s own unit, ruining flooring and personal belongings inside. The master policy doesn’t respond to this at all, since it’s confined to the unit itself rather than shared spaces. This owner’s dwelling and personal property coverage under their own HO-6 policy is what actually pays for these repairs and replacements.
Common Mistakes to Avoid
- Assuming the master policy covers your unit’s interior. It generally doesn’t, and the exact boundary depends entirely on your association’s specific master policy structure.
- Keeping the default loss assessment limit without reviewing it. A low default limit can leave a meaningful gap if your association ever faces a serious shared-area loss.
- Not accounting for renovations when setting dwelling coverage. Upgrades beyond your master policy’s baseline are your responsibility to insure, and an outdated coverage limit can leave real value unprotected.
- Confusing condo insurance with renters insurance. They’re different products; HO-6 includes dwelling and improvement coverage that a renters policy doesn’t, since renters don’t own the unit itself.
Final Thoughts
Condo insurance exists specifically to fill the gap the master policy leaves open, and understanding exactly where that gap sits, based on your specific association’s master policy structure, is the difference between adequate coverage and an unpleasant surprise after a claim. Reviewing your association’s master policy documents, confirming its structure, and setting your loss assessment and dwelling limits accordingly is worth the time it takes, ideally before you need to rely on it.
Disclaimer: This article is for general informational purposes only and does not constitute financial, legal, or insurance advice. Master policy structures, coverage splits, and loss assessment norms vary by HOA, insurer, and state, and can change over time. Review your specific association’s master policy and contact your insurance provider or a licensed insurance professional for advice about your situation.
Sources
- State Farm — “Condo Insurance Basics,” statefarm.com
- Progressive — “What Is Condo (HO6) Insurance?,” progressive.com
- Fannie Mae — Servicing Guide requirements referenced via industry guidance




